Beta Technologies raised about $1.015 billion in gross proceeds in its 2025 IPO. The capital matters because Beta is funding two certification paths and charging infrastructure, but the raise itself does not establish the timing or economics of either aircraft program.

$34.00/share — Beta's IPO price ~29.9M shares — Class A shares offered ~$1.015B — gross IPO proceeds before over-allotment ~83,000 nautical miles — Beta's cumulative flight testing to date 50+ — Beta charging-network sites live across the US and Canada
The roughly $1.015 billion gross raise extends the capital available for Beta's certification, industrialization and infrastructure work. It does not by itself establish aircraft economics or certification timing.
How Beta allocates capital across the CX300 and powered-lift ALIA programs, conformity and production-system work, and charging infrastructure—and whether those investments translate into regulator-accepted milestones.
Beta Technologies priced an upsized initial public offering at $34 per share, offering nearly 29.9 million Class A shares for approximately $1.015 billion in gross proceeds before any underwriter over-allotment. Shares began trading on the New York Stock Exchange on November 4, 2025.
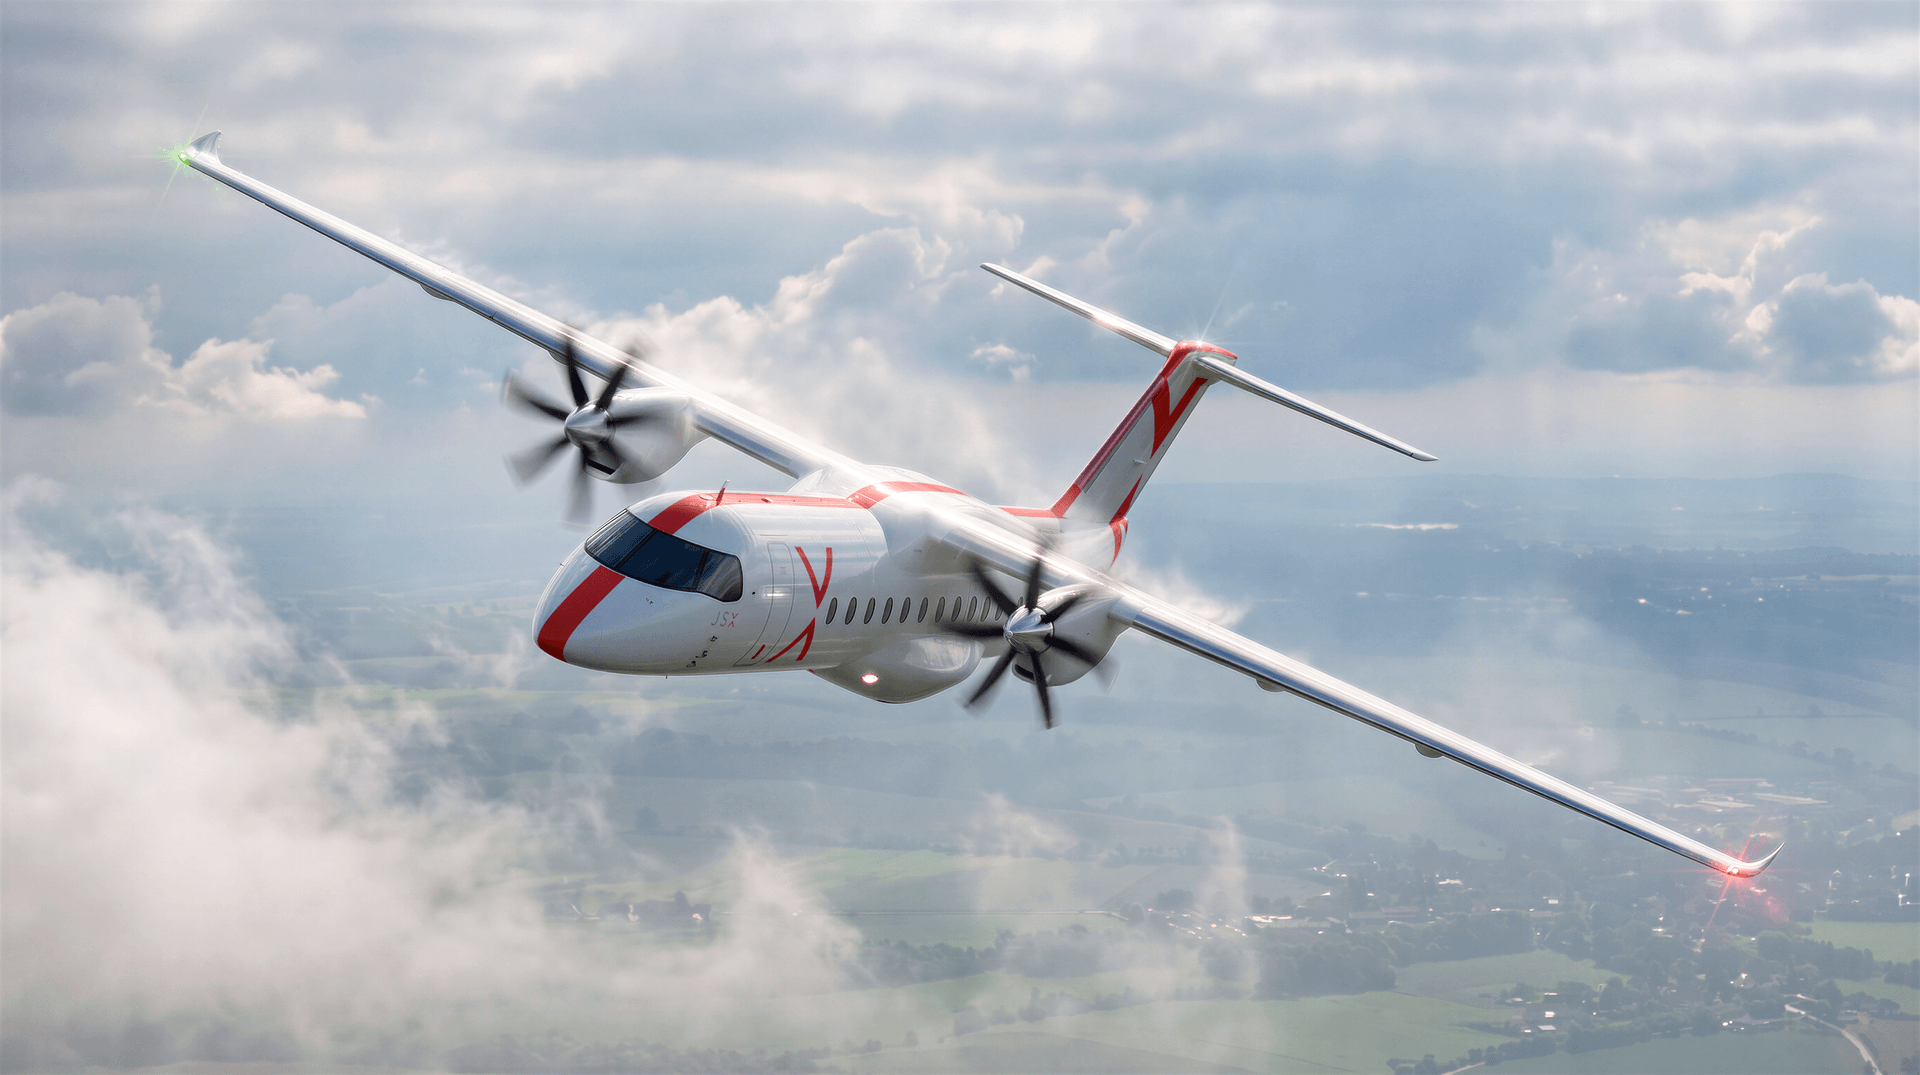
For an aircraft developer, the engineering relevance of the raise is runway. Beta is supporting two distinct certification programs: the fixed-wing CX300 under FAA Part 23, and the vertical-lift ALIA under the powered-lift certification pathway. Certification aircraft, conformity testing, manufacturing systems and continued flight testing require substantial capital before either program reaches mature production.
Beta has also invested in a charging network, with more than 50 sites reported live across the US and Canada at the time of the company's disclosure. That infrastructure can reduce dependence on third-party charging deployment, but its commercial value will depend on utilization, interoperability, operating cost and the pace at which electric-aircraft fleets actually enter service.
The company has reported roughly 83,000 nautical miles of cumulative flight testing. That is evidence of substantial flight activity, but cumulative mileage should not be treated as a proxy for certification completion: regulators approve a design against defined compliance requirements, not a mileage threshold.
Not investment advice. Financing data is included here because certification and industrialization are capital-intensive engineering programs, not as a view on any security.